Founder’s Note: Sam Gatlin always does a great job on the “write what you know” assignment.
He does the kind of research it takes to understand human nature and get to emotional truth.
And Sam knows as well as anybody that the ultimate goal is to manage risk, maximize reward, and make a lot of money in the stock market. – JC
Every fall, my parents get a reminder of just how complicated the American healthcare system really is.
My father is a pharmacist, my mother was a nurse, and together they own and operate a successful independent pharmacy business here in rural Kansas.
And right now, they’re in the middle of one of their busiest times of the year.
Medicare enrollment season.
From October 15 through December 7, millions of Americans can review their Medicare coverage and make changes for the coming year.
For my parents, that means spending countless hours helping patients navigate an incredibly complicated insurance system, comparing prescription drug coverage, deductibles, copays, and pharmacy networks.
And choosing the wrong plan can be an expensive mistake.
A patient might end up paying hundreds or even thousands of dollars more throughout the year simply because their medications aren’t covered as favorably under their new plan.
But here’s something most people probably don’t realize.
The wrong insurance plan can also be devastating for the pharmacy.
Some insurers and their pharmacy benefit managers reimburse independent pharmacies so poorly that my parents can actually lose money filling certain prescriptions.
Imagine running a business where you’re required to purchase inventory, provide a service, and then get paid less than what the product cost you.
Welcome to the wonderful world of American healthcare.
Needless to say, I’ve had a front-row seat to this industry for most of my life, and right now, I’m seeing a compelling setup take shape.
Health Insurance Stocks Are Ready To Run
To track what’s happening in this industry, I created an equal-weight index of the major publicly traded health insurance providers.
It includes UnitedHealth (UNH), CVS (CVS), Elevance Health (ELV), Cigna (CIG), Humana (HUM), Centene (CNC), Molina Healthcare (MOH), Oscar Health (OSCR), Clover Health (CLOV), and several others.
These companies collectively provide healthcare coverage to tens of millions of Americans, making them some of the most important businesses in the entire healthcare system.
And, after years of struggling, their stocks are among the strongest in the market:
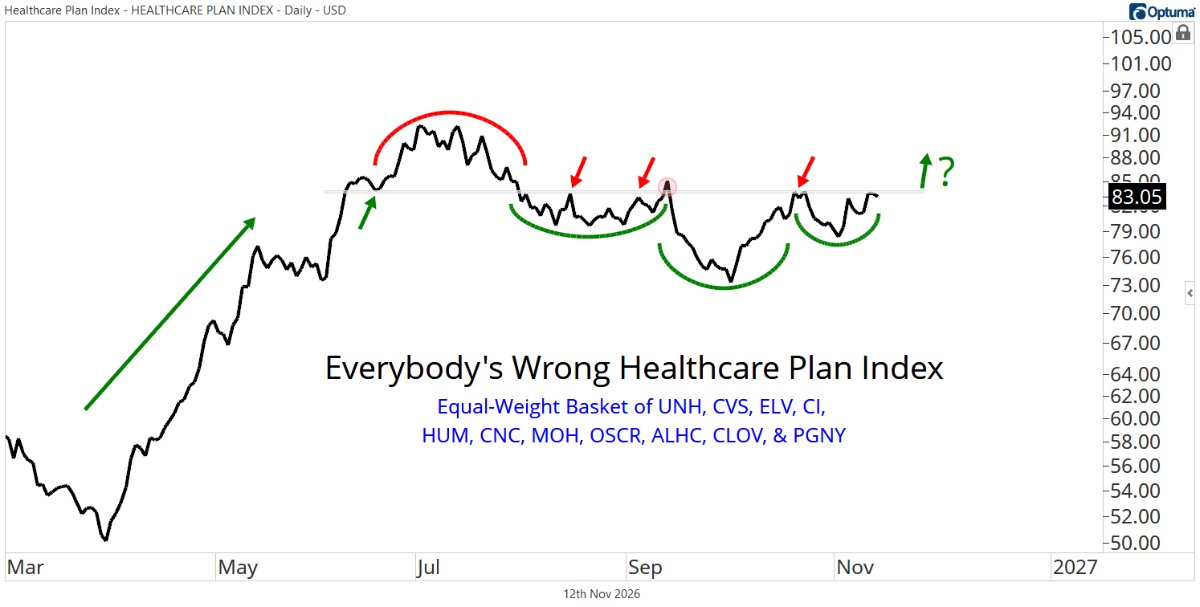
Earlier this year, this index nearly doubled in a matter of months before entering a healthy consolidation phase.
Since then, price has carved out a textbook bullish continuation pattern.
Now the group is pressing against the upper end of that range, and a decisive breakout could kick off another leg higher into the end of 2026.
The market doesn’t care whether these companies are popular, whether healthcare costs are too high, or whether the insurance system is unnecessarily complicated.
It cares about supply and demand.
And, right now, demand for these stocks is overwhelming supply.
Five Stars for Clover
One of my favorite stocks in this group is CLOV, a relatively small Medicare Advantage provider that’s been quietly gaining momentum.
I’ve been accumulating shares for several months, and the recent developments have only strengthened my conviction.
Last month, the Centers for Medicare & Medicaid Services awarded Clover’s PPO Medicare Advantage plans a coveted five-star rating for 2027.
That’s the highest rating available, and only 15 Medicare Advantage prescription drug contracts nationwide earned five stars this year.
It’s a big deal because these ratings influence future Medicare payments and enrollment opportunities, giving highly rated providers meaningful competitive advantages.
And Clover isn’t just improving its quality ratings.
The company recently reported 45% year-over-year membership growth, bringing its Medicare Advantage enrollment to nearly 159,000 members.
That’s remarkable growth in an industry dominated by enormous incumbents.
But you know what I like even more?
The chart:
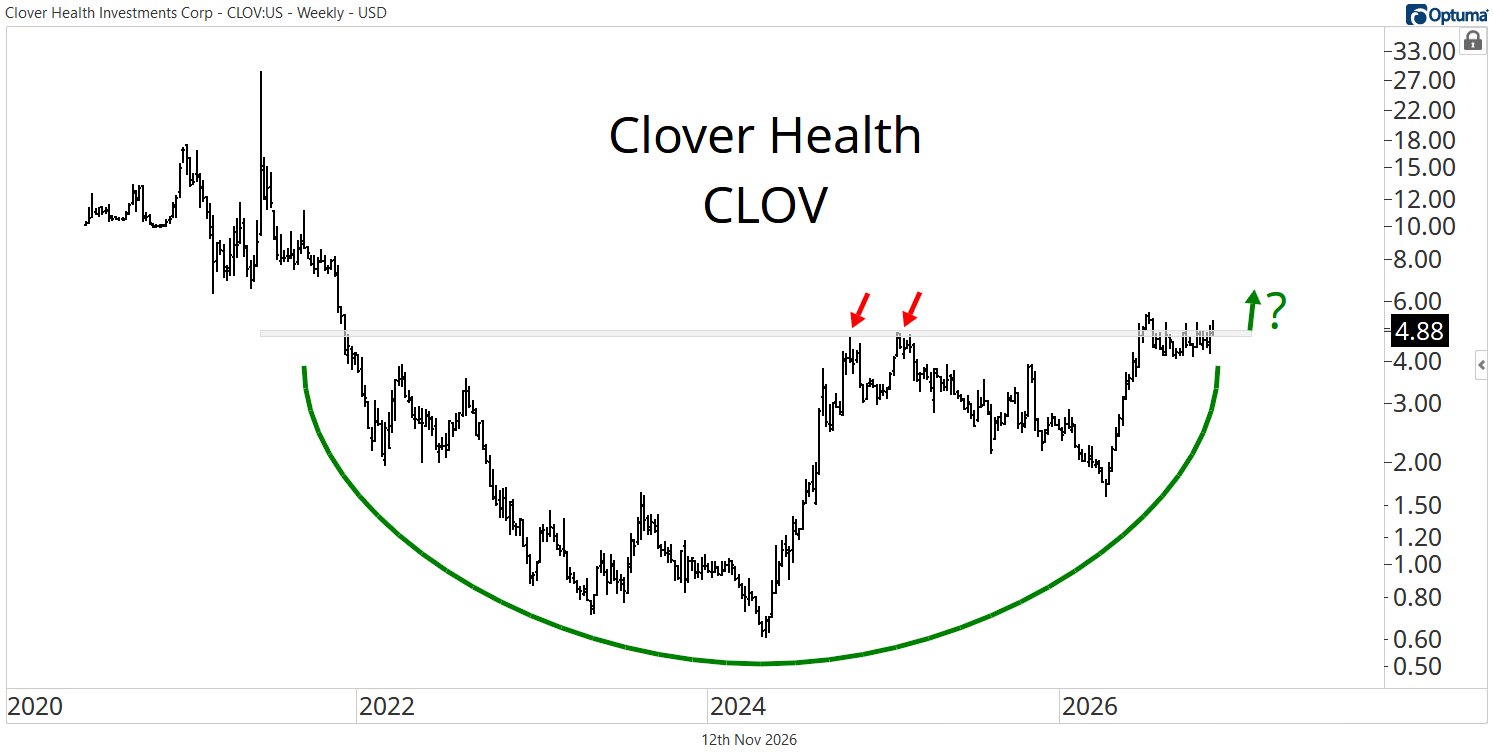
After collapsing from its 2021 highs, Clover spent several years carving out a massive bearish-to-bullish reversal pattern.
Now price is consolidating tightly beneath a shelf of former highs, putting the finishing touches on what could become a MASSIVE breakout.
I’ve been betting on exactly that outcome.
If CLOV can decisively resolve higher from this big base, I think the stock has the potential to double, triple, or even quadruple over time, with the old highs near $20 representing a compelling longer-term objective.
Of course, that’s my thesis, not a guarantee or a recommendation to buy the stock.
But the combination of improving business performance, a five-star Medicare rating, and a massive accumulation pattern is exactly why I’m attracted to CLOV.
Follow the Money
Growing up around healthcare professionals taught me that the industry is much more complicated than most investors realize.
I’ve seen how much work goes into helping patients afford their medications, and I’ve watched my parents navigate an insurance system that often makes their jobs unnecessarily difficult.
But as investors, our job isn’t to decide whether these companies deserve to go higher.
It’s to recognize when they’re going higher and find ways to participate.
Right now, the healthcare plan industry is emerging from a major consolidation, while individual names like Clover Health are showing the kind of strength I want to own.
I’m not interested in fighting that trend simply because health insurance companies aren’t particularly popular.
The market isn’t a popularity contest.
Whether you love these companies or hate them, the charts are telling us something important.
Health insurance stocks are waking up, and I think the next leg higher could be spectacular.
Stay safe out there,
Sam Gatlin
Analyst, Everybody’s Wrong